PM Youth Loan Scheme 2026 Online Apply Pakistan – Eligibility, Loan Amount, Interest Rate & Application Guide
The PM Youth Loan Scheme 2026 Online Apply Pakistan guide explains the eligibility criteria, loan amounts, markup rates, required documents, and application process for eligible Pakistani applicants.
Are you planning to start a small business, expand an existing business, or invest in agriculture but do not have enough money? The PM Youth Loan Scheme 2026 Online Apply Pakistan program may be worth exploring if you meet the eligibility requirements and have a practical business plan.
The Prime Minister’s Youth Business & Agriculture Loan Scheme (PMYB&ALS) is a government-supported financing program designed to help eligible young Pakistanis establish or expand businesses through participating banks. The official program provides three financing tiers, with amounts ranging from up to Rs. 500,000 at 0% markup to a maximum of Rs. 7.5 million at subsidized markup rates. Official scheme website.
In this guide, you will learn about the loan amount, markup rates, eligibility criteria, required documents, online application process, repayment terms, and common mistakes to avoid before applying.
Important: Scheme rules, application availability, and bank requirements may change. Always verify the latest details through the official portal before submitting an application.
What Is the PM Youth Loan Scheme 2026?
The Prime Minister’s Youth Business & Agriculture Loan Scheme is an initiative intended to encourage entrepreneurship, self-employment, and agricultural development in Pakistan.
It supports eligible applicants who want to start a new business or expand an existing one. Applications are submitted online and processed through participating commercial, Islamic, and other eligible financial institutions.
The program may be relevant to people interested in:
- Starting a small shop or retail business.
- Establishing a livestock or dairy farming operation.
- Purchasing eligible machinery or business equipment.
- Launching an IT or e-commerce business.
- Expanding an existing small business.
- Financing eligible agricultural activities.
However, not every expense or business activity will automatically qualify. The bank assesses the proposed business, the applicant’s financial circumstances, and the applicable scheme requirements.
PM Youth Loan Scheme 2026 Loan Amount and Interest Rates
One of the most important things to understand before applying is how the financing tiers work.
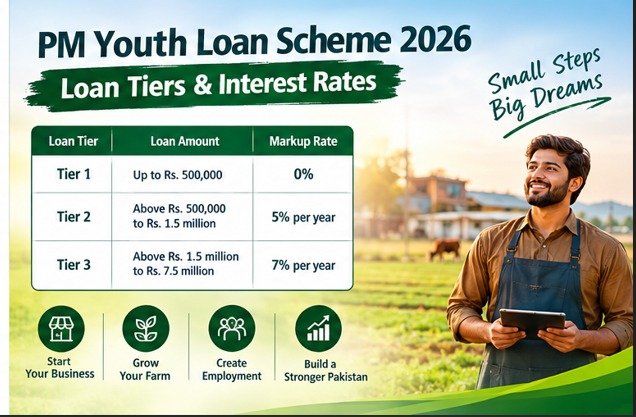
According to the official program website, the scheme has three tiers with different loan limits and markup rates. Official loan details.
| Loan Tier | Loan Amount | Markup Rate |
| Tier 1 | Up to Rs. 500,000 | 0% |
| Tier 2 | Above Rs. 500,000 to Rs. 1.5 million | 5% per year |
| Tier 3 | Above Rs. 1.5 million to Rs. 7.5 million | 7% per year |
These are the published scheme rates; applicants should confirm that the same terms apply to their application when they submit it.
Tier 1: Loan Up to Rs. 500,000 at 0% Markup
Tier 1 is designed for applicants who need a relatively small amount of financing for an eligible business or agricultural activity.
For example, an applicant might need money to purchase shop inventory, acquire essential equipment, or establish a small eligible business.
The published markup rate for this tier is 0%. However, applicants should still confirm the repayment schedule, any applicable charges, and all contractual conditions with the relevant institution.
Who might consider Tier 1?
- Small business startups.
- Applicants with limited initial capital.
- Entrepreneurs who need modest working capital.
- Eligible applicants planning a small agricultural or livestock operation.
The amount you request should be based on a realistic budget rather than simply choosing the maximum available limit.
Tier 2: Loan Above Rs. 500,000 Up to Rs. 1.5 Million
Tier 2 is intended for eligible businesses that require more capital than the first tier provides.
The published markup rate is 5% per year.
This tier may suit applicants who need to purchase equipment, expand a shop, increase inventory, or finance other eligible business requirements.
Before choosing this tier, calculate your startup expenses, expected monthly revenue, operating costs, and ability to repay the financing.
Tier 3: Loan Above Rs. 1.5 Million Up to Rs. 7.5 Million
Tier 3 provides financing for eligible projects requiring a larger investment, with a published markup rate of 7% per year.
Possible uses may include business expansion, eligible machinery purchases, or agricultural development.
Larger financing requests generally require more detailed financial information and may involve additional security requirements under the participating bank’s policies.
Applicants should prepare a clear business plan and provide realistic estimates of income and expenses.
What Is the Loan Repayment Period?
Repayment terms depend on the type of financing, the selected tier, and the applicable bank conditions.
For example, published bank information for the scheme describes working-capital financing periods of up to five years and long-term development financing of up to eight years, with a possible grace period of up to one year for eligible facilities. These terms should not be assumed to apply identically to every loan. Allied Bank scheme information.
Before accepting a loan, ask the bank to explain:
- The repayment period.
- The monthly installment.
- Whether a grace period is available.
- When installment payments begin.
- Whether any processing or other charges apply.
- What happens if a payment is late.
Never calculate your repayment obligation using the markup rate alone. Request the complete repayment schedule before signing the agreement.
PM Youth Loan Scheme 2026 Eligibility Criteria
Before starting your PM Youth Loan Scheme 2026 Online Apply Pakistan application, check the current age requirements, business eligibility, and required documents
Meeting the eligibility criteria is an essential first step. Applicants should review the following requirements before beginning the online application.
1. Age Requirement
The official program generally allows Pakistani citizens aged 21 to 45 to apply, provided they meet the other requirements.
For IT and e-commerce-related businesses, the lower age limit is 18 years. The scheme also specifies an educational requirement for applicants in this category.
For partnerships and companies, special rules apply concerning the age of owners, partners, or directors.
Because these conditions can depend on the business structure, check the official eligibility information before applying. Official eligibility information.
2. Pakistani Citizenship and CNIC
Applicants must meet the citizenship and identity-document requirements of the scheme.
Keep your valid Computerized National Identity Card (CNIC) available. Ensure that your personal details and contact information are accurate and consistent across the application and supporting documents.
3. New and Existing Businesses
The program is intended to support eligible startups as well as existing small and medium-sized businesses.
You do not necessarily need to own an established business to apply. However, if you are proposing a new business, you should be prepared to explain what you intend to do, how much money you need, and how the business will generate enough income to meet its expenses and repayment obligations.
Applicants with existing businesses should be prepared to provide relevant information about their current operations and financial performance.
4. Eligibility for Agriculture and Livestock
Agricultural financing is available for eligible activities under the scheme’s applicable rules.
Depending on the proposed project and bank assessment, these activities may include livestock, dairy farming, poultry, crop production, and other eligible agricultural operations.
Applicants should identify the exact purpose of financing and confirm whether their proposed expenses qualify under the relevant agricultural financing requirements.
5. Who May Not Qualify?
An application may be unsuccessful if the applicant:
- Does not meet the applicable age or citizenship requirements.
- Provides inaccurate or incomplete information.
- Cannot provide required supporting documents.
- Proposes an ineligible business or expense.
- Does not satisfy the bank’s assessment requirements.
- Has insufficient repayment capacity under the bank’s evaluation.
Meeting the basic age and identity requirements does not guarantee loan approval.
Documents Required for PM Youth Loan Scheme 2026
Preparing the necessary information before starting the form can make the application process easier.
The exact requirements may vary depending on the business type, financing tier, and bank.
Personal Information
Prepare the following information where applicable:
- Valid CNIC.
- Mobile number registered in your own name.
- Email address.
- Residential address.
- Business address, if available.
- Personal and financial details requested in the official form.
The official application portal specifically states that the mobile number used for bank communication must be registered in the applicant’s name. Official application form.
Business Information
You may need to provide:
- Business name and type.
- Business location.
- Details of the proposed business activity.
- Estimated startup costs.
- Equipment and inventory expenses.
- Expected monthly sales and operating costs.
- Details of any existing business.
- Relevant financial or business records.
Financial and Supporting Documents
Depending on your circumstances, the bank may request:
- Bank account statements or account details.
- Business feasibility report or business plan.
- Income and expense information.
- Tax registration or NTN details, where required.
- Partnership or company documents, if applicable.
- Guarantor or collateral documents, where applicable.
- Agricultural or property-related documents for relevant projects.
Practical tip: Do not assume that every document on a general checklist is mandatory for every applicant. Follow the requirements shown on the official application form and those communicated by the bank handling your application.
How to Apply for PM Youth Loan Scheme 2026 Online in Pakistan
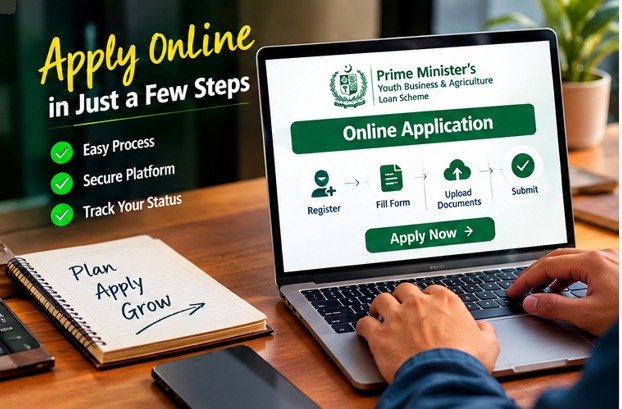
Applications are submitted online through the official Prime Minister’s Youth Programme portal. The program website states that applications must be submitted online rather than through a physical application form at a bank branch.
To complete the PM Youth Loan Scheme 2026 Online Apply Pakistan process, visit the official portal, enter your details carefully, and follow the instructions provided on the website.
Step 1: Open the Official Application Portal
Visit:
You can also access the application form through the official portal’s application section.
Always check the website address carefully before entering personal or financial information.
Step 2: Register or Sign In
Create an account or sign in as instructed by the portal.
Use your own mobile number, registered in your name, because the bank may use it to communicate with you about your application.
Make sure your contact information is correct and accessible.
Step 3: Enter Your Personal Details
Complete the requested personal information, including your identity details, address, and other required fields.
Review your CNIC information carefully. Incorrect information can cause verification problems or delay processing.
Step 4: Provide Your Business or Agricultural Details
Describe the business you want to establish or expand.
Explain what products or services you will provide, who your potential customers are, and where the business will operate.
If you are applying for agricultural financing, specify the proposed activity and explain how the requested funds will be used.
Avoid vague descriptions such as “business investment.” A clear explanation makes it easier to understand your project’s purpose.
Step 5: Enter Your Financial Information
Provide the required estimates for business income, business expenses, household expenses, and other relevant income.
For a new business, prepare reasonable estimates based on local prices, expected sales, and operating costs.
For an existing business, use actual records wherever possible.
Do not exaggerate your expected profit simply to justify a larger loan.
Step 6: Review and Submit Your Application
Before submitting, check every section.
Confirm that your requested loan amount matches your proposed expenses and that the details in the application are consistent with your supporting documents.
Save your application reference number or confirmation details if provided.
Step 7: Follow Up on Your Application
Use the official portal’s available facilities to check your application status, where supported.
Keep your phone active and respond to legitimate requests for additional information.
If the application is delayed, contact the bank or official support channel associated with your application.
Important: Submission of an online form does not mean the loan has been approved. Approval depends on verification, the bank’s assessment, and the applicable program conditions.
How to Prepare a Strong Business Plan
A business plan explains how you intend to use the financing and how the business may generate enough money to operate and repay the loan.
It does not need to be unnecessarily complicated, but it should be realistic and specific.
1. Explain Your Business Idea
Describe the business in a few clear sentences.
For example, if you want to open a small grocery shop, explain the location, target customers, products, and why you believe there is demand.
For a livestock business, explain the proposed animals, feed arrangements, housing, veterinary costs, and expected sales.
2. Calculate the Required Investment
List the main expenses.
A small retail business might require money for inventory, shelves, equipment, rent, and initial working capital.
A livestock business may require spending on animals, housing improvements, feed, water facilities, veterinary care, and other operating expenses.
Use actual quotations or local market prices wherever possible.
3. Estimate Monthly Income and Expenses
Prepare a simple financial estimate that includes:
- Expected monthly sales or revenue.
- Purchase or production costs.
- Rent and utility expenses.
- Salaries, if applicable.
- Feed, transport, or maintenance expenses.
- Household expenses, where requested.
- Expected money remaining after expenses.
Distinguish revenue from profit. A business that generates Rs. 200,000 in monthly sales does not necessarily earn Rs. 200,000 in profit.
4. Explain How You Will Repay the Loan
Your projected income should leave enough money to cover installments and unexpected expenses.
Consider what would happen if sales were lower than expected, feed prices increased, or the business took longer to become profitable.
A realistic repayment plan is more useful than an optimistic estimate that ignores business risks.
5. Get Help If Needed
The Small and Medium Enterprises Development Authority (SMEDA) has been assigned an advisory role under the program. Its official resources may help eligible applicants prepare a business plan or understand the financing process.
Visit SMEDA’s official website for business guidance and available support.
Businesses You May Consider Starting With a PM Youth Loan
The right business depends on your experience, location, available resources, local demand, and repayment capacity.
Here are several possibilities to research before choosing a project.
Small Retail Shop
A grocery, general store, or other small retail business may be suitable where there is sufficient local demand.
Before applying, estimate the cost of inventory, shop setup, rent, utilities, and replenishment.
Livestock and Dairy Farming
Eligible applicants may explore livestock or dairy-related financing.
However, calculate animal purchase costs, feed, veterinary care, housing, water, labor, and expected production carefully.
Milk production, animal health, feed prices, and local selling prices can significantly affect profitability.
Poultry Farming
Poultry projects require careful planning around chicks, feed, housing, vaccination, electricity, and market prices.
Do not rely on an estimated selling price without checking local market conditions and the relevant production costs.
IT and E-Commerce Business
Eligible applicants may consider digital services, online selling, or other qualifying IT and e-commerce activities.
Potential expenses may include equipment, software, eligible business infrastructure, and working capital.
Confirm that the proposed activity and expenses qualify under the scheme.
Agriculture-Related Business
Applicants may also investigate eligible crop-related, machinery, and other agricultural activities.
The financing requirements depend on the proposed activity and the applicable agricultural financing rules.
Remember: These are examples of potential business ideas, not a promise that the bank will approve every project or expense.
How to Check PM Youth Loan Scheme 2026 Application Status
After submitting your application, you may want to know whether it is being reviewed, whether additional documents are required, or whether a decision has been made.
To follow up:
- Visit the official PM Youth Programme portal.
- Sign in using the available account or application facilities.
- Look for an application-status or tracking option, if available.
- Keep your application reference number ready.
- Contact the relevant bank through its official channels if you need clarification.
The exact status labels and tracking facilities may depend on the portal’s current functionality.
If the bank requests further information, respond using verified official contact channels. Never share your banking passwords, one-time passwords (OTPs), or other security credentials with an unofficial agent.
Common Reasons for Loan Application Rejection
A carefully prepared application may reduce avoidable mistakes, although no applicant can guarantee approval.
Incomplete or Incorrect Information
Missing fields, inconsistent identity details, or inaccurate financial information may cause delays or lead to rejection.
What to do: Review every section before submitting and ensure that your information matches your supporting documents.
Weak Business Plan
A proposal that does not explain the business model, costs, customers, or repayment strategy may be difficult for a bank to assess.
What to do: Explain exactly how the business will operate and prepare realistic estimates.
Unrealistic Income Projections
Overestimating sales or ignoring operating costs can make a business plan appear unreliable.
What to do: Use local prices, actual records, and conservative estimates.
Insufficient Repayment Capacity
The bank needs to assess whether the proposed business and the applicant’s financial circumstances support the repayment obligation.
What to do: Request an amount that matches your actual needs and demonstrate how installments could be paid.
Missing Supporting Documents
Applications may require additional documents depending on the business and financing tier.
What to do: Follow the current checklist and respond promptly to legitimate document requests.
Failure to Meet Eligibility Requirements
An applicant may have a good business idea but still fail to satisfy the scheme’s eligibility rules.
What to do: Confirm the applicable age, identity, business, and financing conditions before applying.
What Should You Do If Your Application Is Rejected?
If your application is unsuccessful, do not immediately submit another application without understanding the reason.
First, contact the relevant bank through its official channels and ask whether it can explain the decision or identify any correctable issue.
Then:
- Review the reason for rejection.
- Correct any inaccurate or incomplete information.
- Prepare missing documents, if the bank permits you to provide them.
- Improve your business plan and financial estimates.
- Check whether you meet the current eligibility conditions.
- Confirm whether and when another application is permitted.
Reapplying does not guarantee approval. Follow the bank’s instructions and the applicable program rules.
Frequently Asked Questions About PM Youth Loan Scheme 2026
1. Is the PM Youth Loan Scheme open for applications in 2026?
The official program website provides information about the scheme and an online application facility. However, applicants should check the live portal for the latest application availability, any deadlines, and current conditions before proceeding.
Official website: https://pmybals.pmyp.gov.pk/
2. What is the maximum loan amount under the PM Youth Loan Scheme?
The published maximum financing limit is Rs. 7.5 million, equivalent to Rs. 75 lakh, under Tier 3. Approval depends on eligibility, the proposed business, financial assessment, and applicable bank requirements.
3. Is the PM Youth Loan Scheme interest-free?
Tier 1 has a published markup rate of 0%. Tier 2 carries a published rate of 5% per year, and Tier 3 carries a rate of 7% per year. Applicants should verify the applicable terms and any charges before signing an agreement.
4. Can I apply without an existing business?
Yes, eligible applicants may apply for financing for a proposed new business. You should be ready to explain the business idea, investment requirements, expected income, and repayment plan. The bank will assess the proposal under the applicable rules.
5. Can I apply for livestock or dairy farming?
Eligible agricultural activities may be covered by the scheme. Whether a particular livestock or dairy project qualifies depends on the applicable agricultural financing rules, the requested expenses, and the bank’s assessment.
6. Is collateral required for the PM Youth Loan Scheme?
Security requirements depend on the financing tier and the relevant bank’s rules. Published scheme information indicates that Tier 2 financing may be secured by the borrower’s personal guarantee, while Tier 3 can involve security requirements under the bank’s policy. Confirm the precise terms before applying.
7. How long does loan approval take?
There is no single approval time that can be guaranteed for every application. Processing depends on the bank, completeness of the documents, verification requirements, and the complexity of the proposed business.
8. Can salaried individuals apply?
Having a salary does not, by itself, establish eligibility or guarantee approval. The scheme focuses on eligible business and agricultural financing. Applicants should confirm whether their proposed business and personal circumstances meet the current requirements.
9. Can women apply for the PM Youth Loan Scheme?
Women who satisfy the applicable eligibility requirements may apply. Published bank information also describes a program target under which 25% of loans are allocated to women borrowers. Applicants should verify the current scheme rules and available financing arrangements.
10. How can I check my application status?
Use the official portal’s available account or tracking facilities and keep your application reference number ready. If you cannot find the relevant information online, contact the bank handling your application through its official support channel.
11. Is there an application fee?
Fees and charges can depend on the applicable scheme instructions and bank. Check the current official application information and the relevant bank’s published schedule of charges. Do not pay an unofficial agent who promises guaranteed approval.
12. What is the official website for the PM Youth Loan Scheme?
The official program website is:
Use the official website to review the current scheme details and access the application facility.
Final Verdict: Should You Apply for the PM Youth Loan Scheme 2026?
f you meet the eligibility requirements, use the official portal to explore the PM Youth Loan Scheme 2026 Online Apply Pakistan process and review the latest application instructions.
Before applying, understand the financing tiers, verify the applicable markup rate, calculate your expected expenses, and prepare a realistic repayment plan. A smaller loan that matches your actual requirements may be more manageable than borrowing the maximum available amount.
Most importantly, verify the current eligibility rules and application availability through the official program portal. Do not assume that every applicant will qualify, that every business expense will be accepted, or that approval is guaranteed.
Ready to explore the scheme? Visit the official PM Youth Loan Scheme website to review the current details and begin your application if you are eligible.